back to Articles
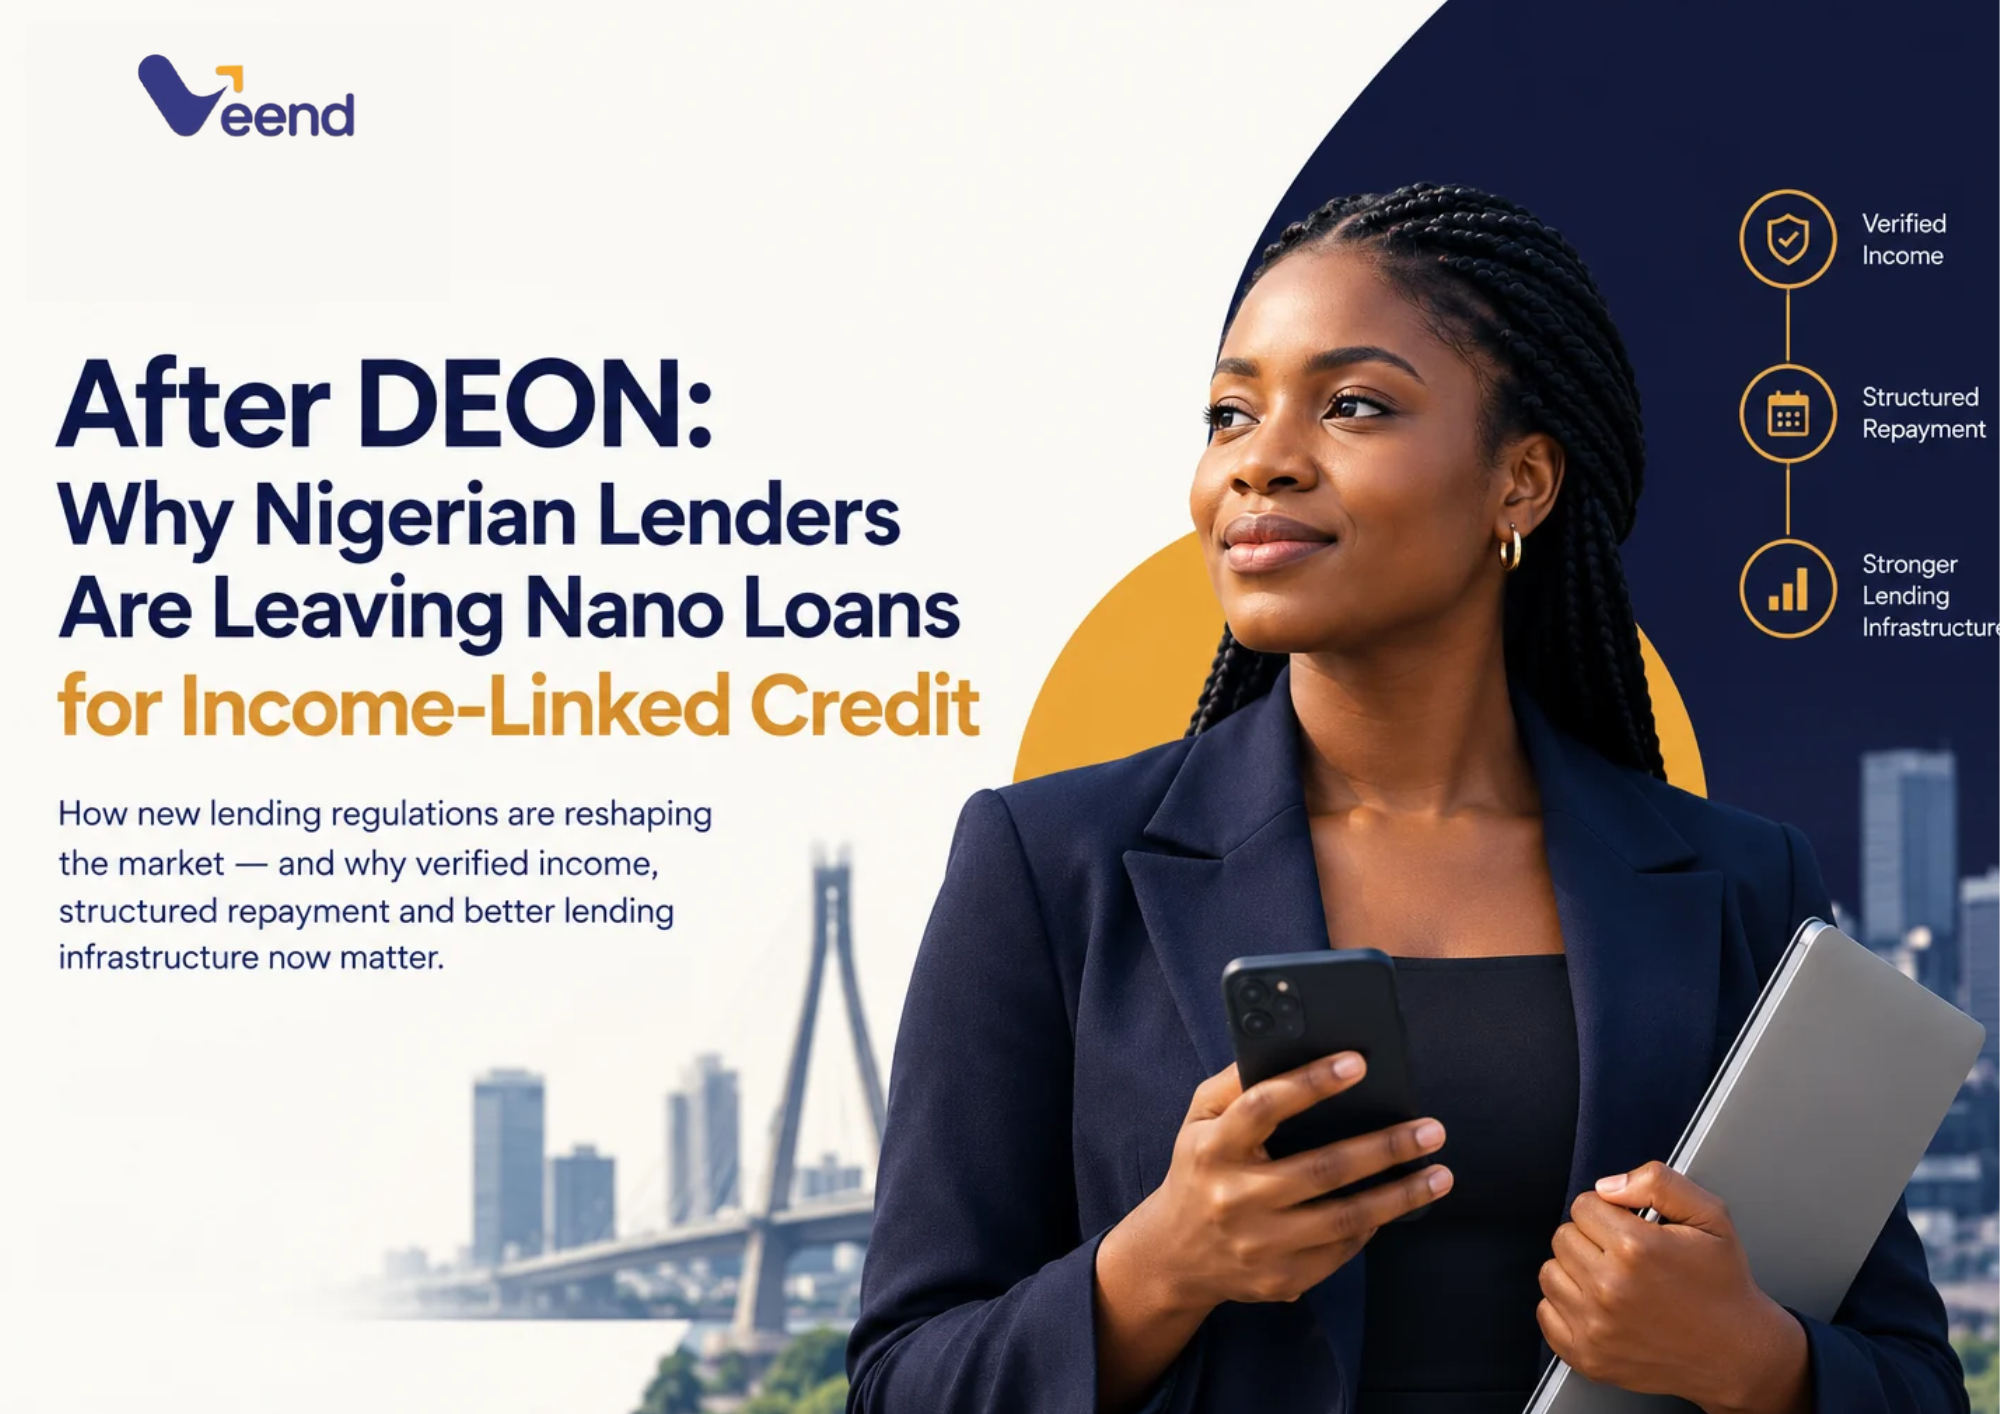
After DEON: why Nigerian lenders are leaving nano loans for income-linked credit
Pius Henry
Marketing Lead
On 20 July 2026, the Federal High Court in Lagos dismissed the suit the Wireless Application Service Providers Association of Nigeria had filed against the FCCPC. The ruling upheld the Digital, Electronic, Online or Non-Traditional Consumer Lending Regulations, 2025, usually shortened to DEON, and the Commission resumed enforcement straight away.
Seven weeks later the effect is visible. Nairametrics reported on 9 September that digital lenders are scaling back unsecured instant loans and chasing borrowers with verifiable income, credit history and predictable cash flow. The number of FCCPC-registered lenders has climbed to 525, with another 33 on waivers because they already hold CBN licenses. 112 apps sit on the Commission's watchlist, and 54 have been pulled from the Google Play Store.
For anyone lending in Nigeria, the question is no longer whether the rules will stick. It is how the market reorganizes around them.
Who DEON covers, and who it doesn't
DEON applies to anyone providing or facilitating non-traditional consumer lending: loan apps, platforms that advance value on credit, and the agents and intermediaries around them. Lenders must register, follow Nigeria's data protection law, report consumer complaints every quarter, and stop tying loans to unrelated products.
Some lenders sit outside it. According to Aluko & Oyebode's summary of the DEON Guidelines, the rules exclude institutions licensed and regulated by the CBN (which includes microfinance banks), lending arrangements between employers and employees, and registered cooperatives.
So an MFB is not directly bound by DEON. It is still affected, because DEON is changing what its competitors can offer and who they are willing to lend to.
Why the nano-loan math stopped working
The 30-day, unsecured nano loan was built on two assumptions: acquisition was cheap, and aggressive recovery would cover the defaults. DEON removed the second assumption.
Under the current rules, abusive collection is sanctionable, and the FCCPC has taken a zero-tolerance position on harassment. One digital lending executive told Nairametrics that the worst a registered lender can now do to a defaulter is blacklist them, which may stop the borrower getting credit elsewhere but "does not bring back the money owed."
Babatunde Akin Moses, CEO of Sycamore, explained the cost side with a simple comparison. Lend ₦1 million to one borrower and you assess and manage one customer. Lend the same ₦1 million as ₦5,000 loans and you have 200 customers to onboard, assess, monitor and follow up. Each of those carries fraud risk, funding cost and recovery effort, and the operating cost per naira lent climbs fast.
Moses was also clear that demand for small credit hasn't gone away. Gbemi Adelekan, President of the Money Lenders Association, said loan applications have actually risen as households look for short-term credit to stretch their income. Nobody is saying the need disappeared. The old way of serving it just stopped paying.
Where lenders are moving
Adelekan described the move plainly: away from unsecured nano loans and toward tenured, structured installment loans "with certainty of source and deduction of income." Lenders are also leaning into business loans where repayment can be tied to verifiable cash flow.
In practice that means three shifts:
- Larger tickets over longer tenures, which spread origination and monitoring cost across more naira.
- Underwriting on verified income or business transactions rather than phone data and a guess.
- Repayment designed at the start, through deduction at source or linked cash flow, instead of recovery after default.
What this means for MFBs and institutional lenders
If you are an MFB or an institutional lender, DEON's pressure on app lenders creates an opening, as long as you're set up to use it.
Demand is being released. Borrowers that app lenders now decline or price out still need credit. Lenders who can verify income cheaply will be the ones able to serve them.
Verification has to move upstream. Once aggressive recovery is off the table, the underwriting decision carries more of the risk. The question to ask before disbursement is: where does the repayment come from, and can we see it?
Recovery belongs in the product design. A loan whose repayment is deducted from salary or linked to a known cash flow doesn't depend on chasing the borrower later. Your portfolio quality starts at origination.
Unit economics favor fewer, better-sized loans. Moses's 200-borrower example applies to any lender. If your cost to originate and service a loan is roughly fixed, ticket size and tenor drive margin.
Compliance posture is now a selling point. Borrowers, partners and funders are watching who is registered and who is on the watchlist. Being able to show clean, documented lending and collection practices matters more than it did a year ago.
Where Veend fits
VeendHQ gives financial institutions the infrastructure and liquidity to run lending with automated recollection from source, starting with payroll-linked lending to federal and Remita-paid workers. That is the lending model the market is now moving toward: income you can verify, and repayment that doesn't depend on chasing anyone.
If your institution is rethinking its consumer book after DEON, Veend's team is happy to walk through how income-linked lending could fit your portfolio. veendhq.com/financial-institutions